What Is an Uninsured Motorist Claim and How Does It Work?

What Is an Uninsured Motorist Claim and How Does It Work?

What Is an Uninsured Motorist Claim and How Does It Work?

A car accident is already overwhelming—but it becomes even more financially stressful when the at-fault driver does not have insurance. Unfortunately, this situation is more common than many people realize. When this happens, your financial recovery depends on something called an uninsured motorist claim.

An uninsured motorist claim allows you to seek compensation through your own insurance policy when the negligent driver cannot pay for your losses. It is one of the most important protections available under modern auto insurance policies.

At More 2 You Law, we help injured victims understand their rights and navigate the complex insurance claim process so they can recover fair compensation for medical bills, lost wages, and pain and suffering.

This guide explains everything you need to know about uninsured motorist claims, including how they work, what they cover, and how to maximize your settlement.

Whether it’s gathering evidence, negotiating with insurance companies, or representing clients in court, More 2 You handles every aspect with utmost professionalism and dedication.

Understanding an Uninsured Motorist Claim

An uninsured motorist claim (UM claim) is a type of insurance claim you file with your own insurance company when the driver responsible for your accident has no liability insurance.

In simple terms, it steps in when the at-fault driver cannot.

This coverage typically applies in situations such as:

  • The at-fault driver has no auto insurance
  • The driver flees the scene (hit-and-run accident)
  • The driver’s insurance policy is invalid or expired
UM claim

Why UM Coverage Exists

Uninsured motorist coverage exists to protect responsible drivers from bearing the financial burden of someone else’s negligence. Without it, victims would often be forced to pay medical expenses and vehicle repairs out of pocket.

Uninsured Motorist vs Underinsured Motorist Coverage

It’s important to distinguish between two closely related concepts:

Uninsured Motorist Coverage (UM)

This applies when the at-fault driver has no insurance at all.

Underinsured Motorist Coverage (UIM)

This applies when the at-fault driver has insurance, but not enough coverage to fully compensate your damages.

For example, if your medical bills total $50,000 but the at-fault driver only carries $25,000 in liability coverage, your UIM coverage may help cover the difference.

Together, UM and UIM coverage provide a crucial financial safety net after serious accidents.
Uninsured Motorist in Alabama

When Can You File an Uninsured Motorist Claim?

You may be eligible to file an uninsured motorist claim in several scenarios:

1. Car Accidents with Uninsured Drivers

If the driver who caused the crash has no liability insurance, you can file a UM claim with your own insurer.

2. Hit-and-Run Accidents

If the at-fault driver leaves the scene and cannot be identified, your policy may treat this as an uninsured motorist situation.

3. Expired or Invalid Insurance Policies

If the other driver’s insurance is not valid at the time of the accident, UM coverage may apply.

4. Pedestrian or Bicycle Accidents

If you are hit by an uninsured driver while walking or cycling, you may still qualify for UM benefits.

Step-by-Step Process of Filing an Uninsured Motorist Claim

Understanding the claim process can help you avoid delays and mistakes.

Step 1: Report the Accident Immediately

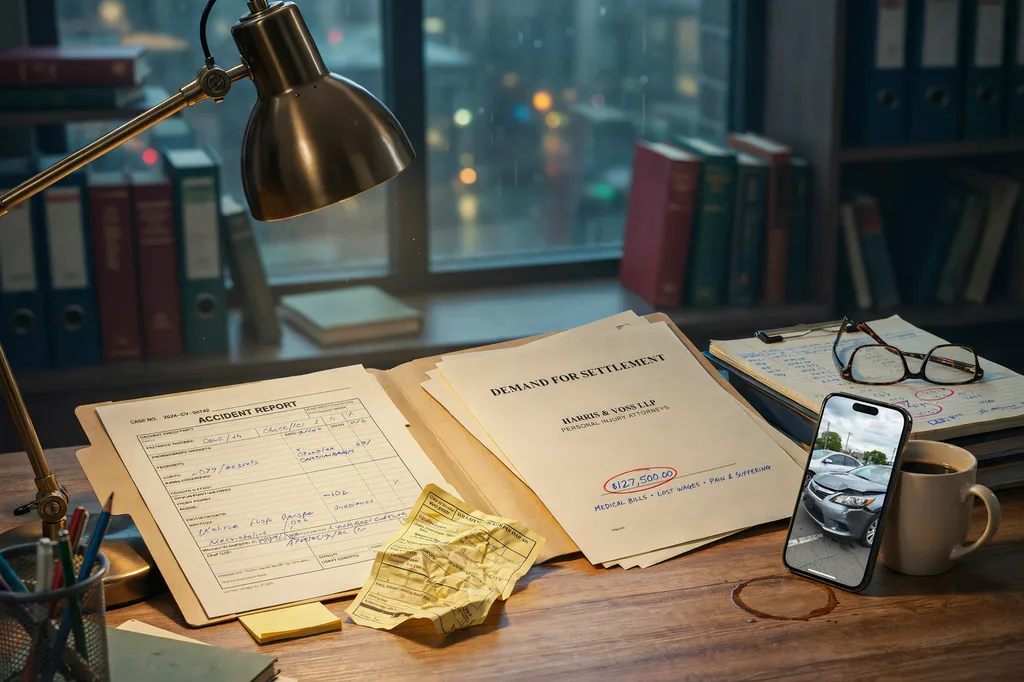
Call the police and ensure a formal accident report is created. This document is essential for your claim.

Step 2: Notify Your Insurance Company

You must inform your insurer that you intend to file an uninsured motorist claim. Timely reporting is critical.

Step 3: Gather Strong Evidence

Evidence strengthens your claim and includes:

  • Police reports
  • Photos of the accident scene
  • Medical records and bills
  • Witness statements
  • Vehicle damage reports

Step 4: File the Claim

You submit your uninsured motorist claim with all supporting documents to your insurance company.

Step 5: Insurance Investigation

The insurer evaluates:

  • Fault determination
  • Extent of injuries
  • Policy coverage limits
  • Validity of medical treatment

Step 6: Settlement Negotiation

Once the insurer completes its review, they may offer a settlement. You can accept or negotiate for a higher amount—often with legal support.
accident victims

What Does an Uninsured Motorist Claim Cover?

A successful UM claim may provide compensation for several types of damages.

Medical Expenses

This includes all injury-related medical costs such as:

  • Emergency treatment
  • Hospital stays
  • Surgery
  • Physical therapy
  • Prescription medications
  • Future medical care

Lost Income

If your injuries prevent you from working, you may recover:

  • Lost wages
  • Reduced earning capacity
  • Long-term disability income loss

Pain and Suffering

Non-economic damages can include:

  • Physical pain
  • Emotional distress
  • Anxiety after the accident
  • Reduced quality of life

Property Damage

In many policies, UM coverage also helps pay for vehicle repairs or replacement.
car accident lawyer

Why Uninsured Motorist Claims Are Often Underpaid

Even though you are filing with your own insurance company, that does not guarantee fair treatment.

Insurance companies may reduce payouts due to:

Lack of Documentation

Insufficient medical records or accident evidence can weaken your claim.

Disputed Liability

Insurers may argue you were partially or fully at fault.

Questioning Medical Treatment

They may claim your treatment was unnecessary or excessive.

Policy Limit Issues

Many victims misunderstand their actual coverage limits.

Insurance Company Tactics

Delays, low settlement offers, and repeated requests for documentation are common.
More 2 you lawyers

How Fault Impacts an Uninsured Motorist Claim

Even though you are dealing with your own insurance company, fault still matters.

Insurers consider:

  • Police reports
  • Traffic law violations
  • Witness testimony
  • Video or dashcam evidence
  • Accident reconstruction analysis

If liability is disputed, your claim may take longer and require additional evidence.

How Much Is an Uninsured Motorist Claim Worth?

The value of an uninsured motorist claim depends on multiple factors:

  • Severity of injuries
  • Medical expenses (current and future)
  • Lost wages and earning capacity
  • Pain and suffering
  • Insurance policy limits

Example:

A minor injury case may settle for a few thousand dollars, while severe injury cases involving surgery or permanent disability may result in significantly higher compensation.

How a Car Accident Lawyer Can Help Your Claim

Working with a car accident lawyer can significantly improve your chances of receiving fair compensation.

At More 2 You Law, legal support typically includes:

Investigating the Accident

Building a strong case with evidence and expert analysis.

Handling Insurance Companies

Protecting you from unfair tactics and low settlement offers.

Calculating Full Damages

Ensuring all losses are included, such as future medical care and lost earning capacity.

Negotiating Settlements

Fighting for maximum compensation based on your injuries.

Litigation if Necessary

If the insurer refuses to act fairly, legal action may be taken.

Uninsured Motorist Claim vs Personal Injury Lawsuit

It’s important to understand the difference:

Uninsured Motorist Claim

  • Filed with your own insurance company
  • Faster resolution in many cases
  • Based on policy limits

Personal Injury Lawsuit

  • Filed against the at-fault driver
  • May result in higher compensation
  • Can take longer to resolve

In some cases, both options may be pursued strategically depending on the situation.

How Long Does an Uninsured Motorist Claim Take?

The timeline varies depending on:

  • Severity of injuries
  • Complexity of evidence
  • Insurance company cooperation
  • Disputes over liability or damages

Simple cases may resolve within weeks, while complex cases can take several months or longer.

Having legal representation often helps speed up the process by preventing unnecessary delays.

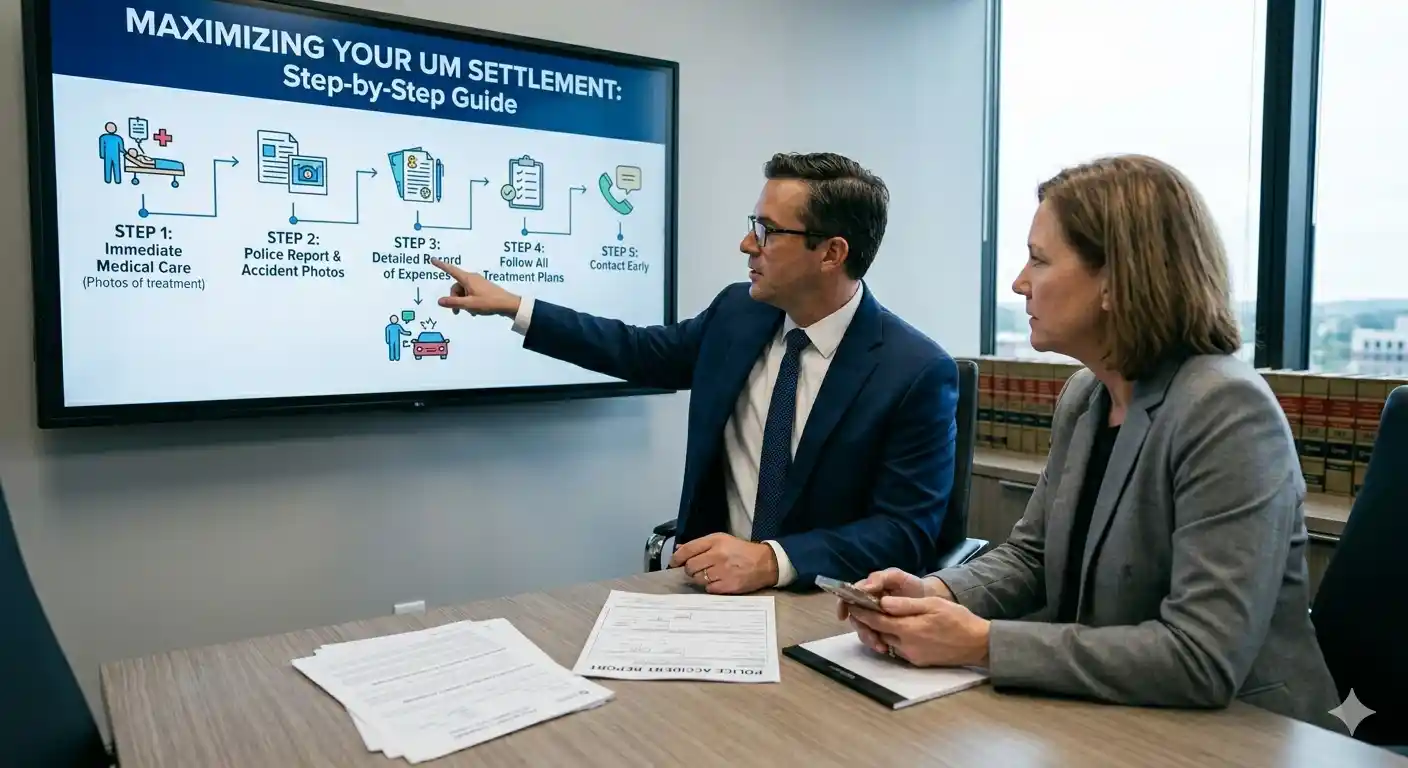
Tips to Strengthen Your Uninsured Motorist Claim

To improve your chances of success:

  • Seek immediate medical attention
  • Keep detailed records of all expenses
  • Follow all treatment plans
  • Document injuries with photos
  • Avoid discussing your case on social media
  • Contact a lawyer early

These steps help build a stronger and more valuable claim.

Why Choose More 2 You Law for Your Case?

Dealing with an uninsured driver can be financially devastating—but you don’t have to handle it alone.

More 2 You Law is committed to helping accident victims recover the compensation they deserve through aggressive negotiation and personalized legal support.

We focus on:

  • Protecting your rights
  • Maximizing your settlement
  • Handling insurance companies for you
  • Reducing stress during recovery

Our goal is simple: help you move forward financially and physically after an accident.

Conclusion: 

An uninsured motorist claim is one of the most important protections available to drivers today. It ensures that you are not left financially responsible for someone else’s negligence.

However, successfully navigating the insurance claim process requires strong evidence, careful documentation, and often professional legal guidance.

If you’ve been injured in an accident involving an uninsured or underinsured driver, understanding your rights is the first step toward recovery—and taking action quickly can make a major difference in your outcome.

FAQs

1. Can I file an uninsured motorist claim if I was partially at fault for the accident?

Yes, in many cases you still can. Even if you share some responsibility for the crash, you may be eligible for compensation under your uninsured motorist claim, depending on your state’s comparative negligence rules and your policy terms. Your payout may be reduced based on your percentage of fault, but it is not always completely denied.

2. Will filing an uninsured motorist claim increase my insurance premium?

Generally, filing an uninsured motorist claim is treated differently than a standard at-fault accident claim. In many cases, insurers do not increase premiums solely because you used UM coverage. However, premium adjustments can still depend on your insurer’s policies, driving history, and claim frequency.

3. What if my insurance company denies my uninsured motorist claim?

If your claim is denied, you are not without options. You can:

  • Request a written explanation for the denial
  • Provide additional evidence or documentation
  • Appeal the decision through your insurer’s internal process
  • Pursue arbitration or legal action if necessary

A denial does not always mean the end of your claim.

4. Is there a time limit to file an uninsured motorist claim?

Yes. Every insurance policy includes a notice requirement and filing deadline, which can vary depending on the insurer and state law. Some policies require you to report the accident “promptly” or within a specific number of days. Missing these deadlines can seriously affect your ability to recover compensation.

5. Can uninsured motorist coverage include compensation for passengers in my car?

Yes. In most cases, uninsured motorist coverage extends to passengers in your vehicle at the time of the accident. They may also be eligible to file a claim under your policy for injuries, depending on the coverage terms and policy limits.


RECENT POSTS
Insurance Bad Faith Attorney: What to Do When Your Insurance Company Treats You Unfairly

Insurance Bad Faith Attorney: What to Do When Your Insurance Company Treats You Unfairly

Insurance Bad Faith Attorney: What to Do When Your Insurance Company Treats You Unfairly

When you need help after a property loss, storm damage, fire, or another covered event, you expect your insurance company to honor its promises. Unfortunately, some insurers delay payments, deny valid claims, or offer unfair settlements that fail to cover the full extent of your losses. An Insurance Bad Faith Attorney can help policyholders challenge these practices and hold insurance companies accountable when they fail to act fairly.

These situations often create financial stress at the worst possible time. Repair costs, temporary housing expenses, and business interruptions continue to grow while policyholders wait for answers. Understanding your rights can help you take action and protect your claim.

Whether it’s gathering evidence, negotiating with insurance companies, or representing clients in court, More 2 You handles every aspect with utmost professionalism and dedication.

What Is Insurance Bad Faith?

Insurance bad faith occurs when an insurance company fails to handle a claim honestly, fairly, or reasonably.

Every insurance policy includes an implied legal obligation known as the duty of good faith and fair dealing. This duty requires insurers to investigate claims properly, communicate with policyholders, and make claim decisions based on facts rather than financial interests.

A denied claim does not automatically mean bad faith occurred. Insurance companies can deny claims when coverage does not apply under the policy. However, bad faith may exist when an insurer intentionally delays a claim, ignores evidence, misrepresents policy language, or refuses to pay a valid claim without a reasonable basis.

Insurance Bad Faith

Why Insurance Bad Faith Matters

Most people purchase insurance for peace of mind. They expect financial protection when unexpected losses occur.

When an insurer fails to honor its obligations, policyholders often face serious financial challenges. Homeowners may struggle to repair damaged property. Business owners may face operational disruptions. Families may find themselves paying expenses that insurance should have covered.

Insurance bad faith can transform a difficult situation into a financial crisis. Recognizing unfair claim practices early can help policyholders protect their interests and seek appropriate legal guidance.

Common Examples of Insurance Bad Faith

Insurance companies use a variety of tactics to reduce claim payouts. Some practices are obvious, while others are harder to identify.

Wrongful Claim Denials

An insurance company may deny a claim without conducting a meaningful investigation.

For example, an insurer may reject a property damage claim before inspecting the damage or reviewing all available evidence. These decisions can prevent policyholders from receiving benefits they paid for through years of premium payments.

Unreasonable Claim Delays

Insurance companies must process claims within a reasonable timeframe.

Repeated requests for information, unexplained delays, and extended periods of silence may indicate problems with claim handling. Delays often place additional financial pressure on policyholders who need immediate assistance.

Lowball Settlement Offers

Some insurers acknowledge coverage but offer significantly less than the amount necessary to repair or replace damaged property.

These offers often encourage policyholders to settle quickly before they fully understand the value of their claim.

Failure to Investigate

A fair claims process requires a thorough investigation.

Insurance companies should inspect damages, review documents, and consider expert opinions. When an insurer ignores critical evidence, policyholders may have grounds to pursue a bad faith claim.

Misrepresentation of Policy Terms

Insurance policies often contain technical language.

Some insurers use complex wording to justify denials or reduce payouts. Policyholders should always request written explanations when coverage disputes arise.

Signs Your Insurance Company May Be Acting in Bad Faith

Many policyholders do not realize they are experiencing bad faith until significant delays or denials occur.

Several warning signs may indicate that an insurance company is acting unfairly:

  • Repeated requests for documents that were already submitted
  • Sudden changes in the reasons for denying a claim
  • Long periods without communication
  • Frequent reassignment of claim adjusters
  • Settlement offers that ignore documented damages
  • Refusal to explain claim decisions in writing

If you notice several of these warning signs, speaking with an Insurance Bad Faith Attorney can help you better understand your legal options.

What Is Post-Claim Underwriting?

Post-claim underwriting occurs when an insurer searches for reasons to deny coverage after a policyholder files a claim.

Instead of evaluating risk before issuing a policy, the company investigates the application only after facing a potential payout.

An insurer may review old applications, supporting documents, or prior records to find reasons to deny benefits. Courts often scrutinize these practices because insurers should evaluate risks before accepting premiums and issuing coverage.

Homeowners Insurance Claims

Why Insurance Companies Sometimes Act in Bad Faith

Most insurance companies handle claims appropriately. However, financial incentives can influence claim decisions.

Insurance companies generate revenue by collecting premiums and managing claim expenses. Every approved claim represents a financial cost to the insurer.

This business model can create pressure to reduce payouts. In some situations, aggressive cost-control measures lead to unfair claim-handling practices that harm policyholders.

Understanding these incentives helps explain why some insurers delay claims, dispute damages, or make inadequate settlement offers.

Types of Insurance Bad Faith Claims

Bad faith can occur in nearly every type of insurance coverage.

Homeowners Insurance Claims

Homeowners frequently encounter disputes involving storm damage, fire damage, water damage, theft losses, and structural damage.

Auto Insurance Claims

Auto insurance disputes often involve vehicle repairs, medical expenses, and liability coverage disagreements.

Insurers may act in bad faith when they deny valid accident claims or delay payments without justification.

Health Insurance Claims

Health insurance disputes may involve denied treatments, delayed approvals, or coverage disagreements.

These issues can create serious financial and medical challenges for policyholders.

Life Insurance Claims

Life insurance disputes often arise when insurers deny death benefits or conduct unreasonable investigations.

Families depend on these benefits during difficult times, making unfair denials especially harmful.

Commercial Insurance Claims

Businesses rely on insurance coverage to protect assets, operations, and financial stability.

Bad faith claim practices can create substantial financial losses and disrupt normal business activities.

How an Insurance Bad Faith Attorney Helps Policyholders

An Insurance Bad Faith Attorney represents policyholders in disputes with insurance companies.

The attorney’s role often includes reviewing policy language, analyzing claim files, gathering evidence, and identifying unfair claim practices. Legal representation can help level the playing field when policyholders face large insurance companies with significant resources.

Attorneys also negotiate settlements, communicate with insurers, and pursue litigation when necessary. Their goal is to protect policyholder rights and seek fair compensation.

At More 2 You Law, we understand how insurance companies evaluate property damage claims and the tactics they may use to minimize payouts. Our team works to help policyholders pursue the benefits they deserve under their policies.

more2you Law PC

How to Prove Insurance Bad Faith

Evidence plays a critical role in bad faith cases.

Policyholders should keep copies of every document related to their claim. This includes emails, letters, claim notes, photographs, invoices, repair estimates, expert reports, and denial letters.

Written communications often reveal how the insurer handled the claim. Documentation can help establish timelines, identify inconsistencies, and demonstrate unreasonable conduct.

An attorney can review these materials and determine whether the insurer violated its legal obligations.

When to Contact a Workplace Injury Attorney

If your injury is serious, if OSHA is involved, or if your employer or their insurance company is already pushing back on your account of what happened, getting legal counsel early is worth considering.

An attorney can make sure that OSHA findings, medical records, and witness statements are actually used effectively in your case — rather than sitting in a file while an insurance company delays or denies your claim. In cases involving documented safety violations or employer negligence, that kind of active legal involvement can be the difference between a fair outcome and a prolonged fight.

If you were injured at work in Alabama or Florida, More 2 You Law can help you understand what you are entitled to and what steps to take to protect your claim from the start.

Insurance Bad Faith Lawsuit

Compensation Available in an Insurance Bad Faith Lawsuit

The compensation available in a bad faith case depends on the facts of the dispute and applicable law.

Policyholders may recover unpaid policy benefits that the insurer wrongfully withheld. Additional damages may include financial losses caused by delayed payments or wrongful claim denials.

Some jurisdictions also permit recovery of attorney fees and litigation costs. Courts may award punitive damages when an insurer engages in particularly serious misconduct.

What to Do After a Claim Denial

A denial does not necessarily end the claims process.

First, request a written explanation from the insurance company. Review the denial carefully and compare it with your policy language.

Next, gather supporting evidence, including photographs, repair estimates, invoices, and expert opinions. Strong documentation often strengthens a disputed claim.

Finally, consider speaking with an Insurance Bad Faith Attorney who can evaluate the insurer’s conduct and explain your legal options.

Speak With More 2 You Law About Your Insurance Claim

Insurance companies have a legal obligation to treat policyholders fairly. When an insurer delays payment, underpays a valid claim, or wrongfully denies coverage, you do not have to accept the decision without question.

At More 2 You Law, we help homeowners, business owners, and policyholders pursue fair treatment from insurance companies. Our team understands the challenges policyholders face after major losses and works to protect their rights throughout the claims process.

If you believe your insurer acted unfairly, document every interaction, preserve all supporting evidence, and seek legal guidance as soon as possible. Early action can help strengthen your position and improve your chances of reaching a fair resolution.

FAQs

What qualifies as insurance bad faith?

Insurance bad faith occurs when an insurer acts unfairly during the claims process. Examples include unreasonable delays, wrongful denials, inadequate investigations, and misleading policy interpretations.

Can I sue my insurance company for denying my claim?

You may have legal options if the insurer denied your claim without a reasonable basis or engaged in unfair claim-handling practices.

How do I know if my claim denial was legitimate?

Review the denial letter and compare it with your policy language. An attorney can help determine whether the insurer’s decision was reasonable.

What evidence helps prove bad faith?

Emails, letters, photographs, repair estimates, expert reports, claim notes, and written explanations from the insurer often help support a bad faith claim.

How long do I have to file a bad faith claim?

Deadlines vary depending on state law and the circumstances of the dispute. Speaking with an attorney promptly helps protect your rights.

Do insurance bad faith attorneys work on contingency?

Many attorneys handle bad faith claims on a contingency-fee basis, but fee arrangements vary by law firm.

How long does an insurance bad faith case take?

The timeline depends on the complexity of the claim, the available evidence, and whether the case settles or proceeds to litigation.

RECENT POSTS

Distracted Driving Accident Lawyer: What Victims Need to Know

Distracted Driving Accident Lawyer: What Victims Need to Know

Distracted Driving Accident Lawyer: What Victims Need to Know

A distracted driver just changed your life in seconds. You’re dealing with injuries, mounting medical bills, missed work, and an insurance company already working against you. Every day you wait, critical evidence disappears and your options narrow. A distracted driving accident lawyer at More2You can step in immediately, preserve that evidence, and fight for every dollar you deserve.

Whether it’s gathering evidence, negotiating with insurance companies, or representing clients in court, More 2 You handles every aspect with utmost professionalism and dedication.

What Is Distracted Driving?

Distracted driving happens any time a driver shifts attention away from the road. It falls into three types: visual (eyes leave the road), manual (hands leave the wheel), and cognitive (mind leaves the task of driving).

Texting is uniquely lethal because it triggers all three at once. But the phone is not the only cause.

Forms of Distraction Beyond the Phone

Drivers cause serious accidents every day while scrolling TikTok, adjusting in-car touchscreens, eating, arguing with passengers, or dealing with pets in the vehicle. Even a hands-free phone call creates dangerous cognitive distraction — keeping hands on the wheel does not keep attention on the road.

If a driver’s distraction caused your crash anywhere in Alabama, Florida, Georgia, or Mississippi, that behavior qualifies as negligence under personal injury law — regardless of whether they received a citation at the scene.

uninsured motorist (UM) coverage
personal injury law

How Dangerous Is Distracted Driving?

In 2023, distracted driving killed 3,275 people across the United States — 8% of all traffic fatalities that year, according to the National Highway Traffic Safety Administration (NHTSA). Another 324,819 people suffered injuries in distraction-affected crashes during the same period.

Texting produces reaction times comparable to a driver with four beers in their system. At 55 mph, a 4–5 second glance at a phone means traveling the full length of a football field without watching the road.

Who Is Most at Risk

Drivers aged 16–45 account for 72% of all distracted driving violations, and male drivers aged 25–34 represent the largest share of fatalities and serious injuries, according to the SafeTREC 2025 Traffic Safety Facts report. Pedestrians face the steepest risk — they account for 25.9% of all fatal and serious injury distracted driving crashes in California, a figure mirrored in high-traffic Southern metros from Birmingham to Miami to Atlanta.

What These Crashes Actually Look Like

A driver glances at an Instagram notification at a red light. The light turns green, traffic ahead slows, but the driver is still looking down. They never brake. They hit the car in front at near-full speed — no skid marks, no evasive action, just a full-speed impact that a one-second decision made inevitable. This is the standard pattern in distracted driving crashes, not an exception.

Two Causes Mostly Ignore

Texting, eating, and GPS use get most of the attention. Two other categories carry serious legal weight.

Rideshare and Delivery Driver Distraction

Uber, Lyft, DoorDash, and Amazon Flex drivers constantly monitor navigation apps and accept incoming job pings while moving through traffic across Florida, Georgia, Alabama, and Mississippi. If a rideshare or delivery driver hit you, the platform may share liability — depending on whether the driver was actively on a job at the time. These cases involve multiple insurance layers and need a lawyer involved from the start. Our rideshare accident attorneys at More2You handle exactly these claims.

When the Driver Was Working

If the driver was on a work call, making a business delivery, or operating a company vehicle, their employer may be liable alongside them under the doctrine of respondeat superior.

That means a second defendant — one with deeper pockets — may owe you compensation. An attorney establishes whether the driver was acting within the scope of employment at the moment of the crash.

Distracted Driving Laws

Injuries Caused by Distracted Driving Crashes

Distracted crashes produce worse injuries than most other collision types for one reason: the at-fault driver takes zero evasive action. No braking. No swerving. Full-speed impact into whatever is in front of them.

Physical Injuries

Traumatic brain injuries carry long-term consequences — memory loss, mood disorders, speech impairment, and learning disabilities. Spinal cord damage can cause partial or complete paralysis. Broken bones, lacerations, internal organ damage, and severe whiplash are among the most common diagnoses.

Psychological Injuries That Factor Into Your Claim

Many victims develop PTSD, chronic anxiety, sleep disorders, and depression after the crash. These are not minor side effects — they are compensable non-economic damages with real dollar value. Documenting psychological impact from the first week of treatment strengthens your claim and raises its total value. Learn more about the full range of damages in personal injury cases.

Distracted Driving Laws in Alabama, Florida, Georgia, and Mississippi

Each of the four states we serve has its own rules. Knowing which law applies to your crash directly affects how your attorney builds the negligence case against the at-fault driver.

Alabama

Under Ala. Code § 32-5A-350, texting while driving is a primary offense — officers can pull a driver over for it alone. Since June 2024, Alabama’s hands-free law also prohibits physically holding a phone while driving, though it remains a secondary offense requiring another traffic violation first. Drivers under 18 face a full ban on all mobile phone use, including hands-free. In 2022 alone, distracted drivers caused 67 fatalities on Alabama roads — a 36% increase from the prior year, according to Drive Safe Alabama.

Florida

Florida Statute § 316.305 bans texting while driving as a primary offense, allowing officers to stop a driver solely for phone use. All handheld phone use in active school and construction zones is prohibited regardless of driver age. Drivers under 18 face a complete ban on all wireless device use. Florida recorded 53,596 distracted driving crashes in 2022 — resulting in 268 deaths and 2,574 serious injuries, according to the Florida Highway Safety and Motor Vehicles data.

Georgia

Georgia’s Hands-Free Georgia Act (O.C.G.A. § 40-6-241) is one of the strongest distracted driving laws in the country. Drivers cannot hold or support a phone with any part of their body — including resting it on a leg. Sending texts, reading emails, recording video, scrolling social media, and touching a phone to control music are all prohibited while the vehicle is moving. A violation of this law is direct evidence of negligence in a civil lawsuit.

Mississippi

Mississippi Code § 63-33-1 bans texting while driving for all drivers. Mississippi does not yet have a comprehensive hands-free law, but that legal gap does not protect distracted drivers from civil liability. If a Mississippi driver’s phone use or other distraction caused your crash, an attorney can prove negligence through phone records, witness accounts, and vehicle data regardless of whether a citation was issued.

The Filing Deadline You Cannot Miss

Every state we serve sets a firm deadline to file a personal injury lawsuit:

  • Alabama: 2 years from the date of injury (Ala. Code § 6-2-38)
  • Florida: 2 years from the date of injury (Fla. Stat. § 95.11, for causes of action after March 24, 2023)
  • Georgia: 2 years from the date of injury (O.C.G.A. § 9-3-33)
  • Mississippi: 3 years from the date of injury (Miss. Code § 15-1-49)

Government vehicle cases in all four states compress those deadlines significantly — sometimes to as little as 90 days to file a formal notice of claim. Miss any deadline and you permanently lose the right to sue, regardless of how strong your case is.

How Fault Is Proven in a Distracted Driving Case

Every negligence case rests on four elements: duty (the driver owed a standard of care), breach (they failed that standard through distraction), causation (the distraction directly caused the crash), and damages (you suffered real losses). Causation is where most cases are decided.

The Evidence That Wins These Cases

  • Cell phone records — subpoenaed from the carrier, showing call logs, SMS timestamps, and data activity at the time of impact. Preservation letters go out immediately before carriers delete records on their standard schedule.
  • Event Data Recorder (EDR) — the vehicle’s black box captures speed, braking input, steering angle, and throttle position in the seconds before impact. No braking in the data is direct proof of inattention.
Distracted Driving Case
  • Traffic cameras, dashcams, and business surveillance — footage showing the driver looking down or failing to react before impact.
  • Lack of skid marks — physical proof the driver never attempted to stop.
  • Witness statements — accounts of phone use, erratic movement, or no reaction to changing road conditions.

How Shared Fault Affects Your Payout

All four states follow contributory or comparative fault rules that directly affect your recovery. Alabama applies contributory negligence — one of the strictest standards in the country. If a court finds you even 1% at fault, you may recover nothing. Florida, Georgia, and Mississippi follow comparative fault rules that reduce your award by your percentage of fault without fully barring recovery in most cases. Insurers in all four states routinely inflate victim fault assignments to minimize payouts. An attorney disputes those figures with documentation from the moment the claim opens.

What to Do After the Crash — and What to Avoid

Take these steps immediately:

  • Call 911 and file a police report, even if the crash looks minor
  • Photograph the scene, vehicle damage, road conditions, and whether skid marks are present or absent
  • Collect witness names and contact details
  • Get medical attention the same day — TBI and soft tissue symptoms often surface days later, not at the scene
  • Write down whether the other driver was holding a phone, looking down, or showed no sign of braking

These mistakes will hurt your case:

  • Posting anything about the accident on social media — insurance adjusters check these accounts
  • Giving a recorded statement to the other driver’s insurer before talking to a lawyer
  • Signing any medical authorization or release before you retain an attorney
  • Taking the first settlement offer — it is nearly always far below what your case is worth
  • Waiting to see a doctor — a gap in treatment gives insurers a written argument that your injuries are not serious

If the Driver Fled the Scene

File a police report immediately. That report activates an investigation using surveillance footage, license plate readers, and witnesses. Check your own insurance policy for uninsured motorist (UM) coverage — it can pay your damages even if the driver is never found. Call a hit-and-run accident attorney at More2You that day, because hit-and-run evidence disappears faster than any other case type.

What Compensation Can You Recover?

Economic damages cover every financial loss you can document: ER and hospital bills, surgery, specialist visits, physical therapy, prescriptions, future medical care, lost wages, long-term loss of earning capacity, vehicle repair or replacement, and rental costs while your car is out of service.

Non-economic damages cover losses that carry no receipt: pain and suffering, PTSD and anxiety, loss of enjoyment of life, scarring and disfigurement, and loss of consortium for your spouse or partner. In serious injury cases these damages often exceed the economic total.

Punitive damages are available when the driver’s conduct was especially reckless — distracted driving combined with drunk driving, for example. Courts in Alabama, Florida, Georgia, and Mississippi all recognize punitive damages in egregious distracted driving cases.

One point that costs victims money: once you sign a settlement, you cannot reopen it — even if your condition deteriorates or new surgery becomes necessary. A medical expert and economist project your future costs before any settlement is signed. That projection is what separates a settlement that covers you from one that runs out in two years.

The evidence your case depends on starts disappearing the moment the crash happens. Phone records get purged on carrier schedules. Dashcam footage gets overwritten within days. Witnesses move on and forget. Contact More2You today for a free consultation — we serve clients across Alabama, Florida, Georgia, and Mississippi with no upfront fees and no obligation.

FAQs

Can I still file a claim if I have no proof the other driver was on their phone? 

Yes. Phone records come from the carrier via subpoena. EDR data, dashcam footage, witness accounts, and the absence of skid marks can all establish distraction without a photo of the phone in hand.

Does Alabama’s contributory negligence rule mean I can’t recover if I was partly at fault?

Alabama’s contributory negligence standard is strict — even slight fault on your part can bar recovery. That is exactly why having an attorney from the start matters. An attorney documents the other driver’s distraction thoroughly and pushes back against any attempt to assign you partial blame without evidence.

How long does a distracted driving accident settlement take in these states? 

Most cases in Alabama, Florida, Georgia, and Mississippi resolve in 4 to 12 months. Severe injuries or disputed liability extend that timeline. Cases that reach trial typically take 1 to 3 years. Getting an attorney involved early shortens the process by locking in evidence before it disappears.

Can I sue if the other driver admitted fault at the scene but the insurer denies it? 

Yes. An admission at the scene is useful but does not bind the insurance company. The insurer responds to documented evidence — police reports, phone records, EDR data — not to what the driver said on the roadside.

What if the at-fault driver had no insurance? 

Your own UM coverage may pay your damages. An attorney also investigates whether an employer, vehicle owner, or government entity shares liability and carries coverage.

Does it cost anything to hire a distracted driving accident lawyer? 

Nothing upfront. More2You works on a contingency fee — you pay nothing unless we win. The fee is a percentage of your final recovery, spelled out in writing before you sign anything.

What is the deadline to file a distracted driving lawsuit in my state?

Alabama, Florida, and Georgia each allow 2 years from the date of injury. Mississippi allows 3 years. Government vehicle cases in all four states can compress those deadlines to as little as 90 days. The clock starts on the day of the crash — contact an attorney before any deadline approaches.

RECENT POSTS

Hit and Run Accident: What It Is, Why It Happens, and What You Can Do

Hit and Run Accident: What It Is, Why It Happens, and What You Can Do

Hit and Run Accident: What It Is, Why It Happens, and What You Can Do

You did everything right — and someone still drove away.

A hit and run accident leaves you injured, shaken, and staring down medical bills while the driver who caused it disappears without a consequence. That helplessness is real. And it happens every 43 seconds somewhere in the United States.

This guide covers the law, your rights, your compensation options in Alabama, Florida, Georgia, and Mississippi, and exactly what to do next. At More 2 You Law, we fight to get you MORE — and we charge less than most firms to do it.

Whether it’s gathering evidence, negotiating with insurance companies, or representing clients in court, More 2 You handles every aspect with utmost professionalism and dedication.

What Is a Hit and Run Accident?

A hit and run accident occurs when a driver involved in a collision leaves the scene without stopping to exchange information, render aid, or wait for police. It does not matter who caused the accident — leaving before fulfilling these obligations is a crime in every U.S. state, including Alabama, Florida, Georgia, and Mississippi.

Hit and runs happen in parking lots, residential streets, and driveways — not just highways. Hitting a parked car and driving away without leaving a note qualifies. A miss-and-run — also called a phantom driver accident — is a related scenario where a driver causes a crash without physically contacting another vehicle, making identification even harder.

auto accident attorney

How Common Are Hit and Run Accidents?

Hit and run accidents are not rare. They are a documented, growing public safety crisis.

  • A hit and run crash occurs every 43 seconds in the United States, according to the AAA Foundation for Traffic Safety
  • 2,932 people died in hit and run crashes in 2022 — up 0.5% from 2021, per the National Safety Council
  • 4.6 out of every 10,000 drivers carry a hit and run violation on record, according to Insurify

Pedestrians and cyclists face the greatest risk. Approximately 1 in 5 pedestrian fatalities over the past decade involved a hit and run driver. Urban areas at night see the highest concentration of incidents.

Why Do Drivers Flee the Scene?

Drivers flee for calculated reasons — not random ones. Understanding these motivations helps investigators build stronger cases.

Fear-based reasons dominate. Drivers under the influence flee to avoid sobriety testing and DUI charges. Those with no valid license, outstanding warrants, or no insurance run because staying triggers immediate legal or financial consequences they cannot face.

Panic and psychology play a major role too. When a collision occurs, the fight-or-flight response activates within milliseconds — flooding the body with adrenaline before rational thought catches up. Research in traffic psychology confirms that even non-at-fault drivers sometimes flee due to acute shock. Young and inexperienced drivers are especially vulnerable to this response.

Social pressures round out the picture. Undocumented drivers fear deportation. Employees driving company vehicles fear termination. Some drivers simply calculate that fleeing protects their insurance record — not realizing the legal consequences of leaving far exceed any premium increase.

Legal Consequences for the Fleeing Driver

Fleeing a crash does not reduce liability. It multiplies it.

Criminal penalties vary by outcome. Property-damage-only hit and runs typically qualify as misdemeanors — fines up to $5,000 and up to one year in jail. When the accident caused injury or death, most states charge a felony, with fines reaching $15,000 and prison sentences up to 15 years. The National Highway Traffic Safety Administration tracks state-by-state penalty structures for reference.

Civil penalties compound the damage. Courts can apply treble damages — tripling the awarded amount — when conduct is deemed egregious. That extra amount typically falls outside insurance coverage, meaning the driver pays out of pocket.

Administrative consequences follow independently. A hit and run conviction typically suspends a driver’s license for 6 months to 3 years. Most states require SR-22 filing before reinstatement, and many insurers cancel policies outright upon conviction.

wrongful death attorneys

State Laws in AL, FL, GA & MS

Penalties and deadlines differ significantly across the four states More 2 You Law serves.

Florida imposes a mandatory minimum four-year prison sentence for a hit and run involving death — with no suspension allowed. Georgia classifies injury hit and runs as felonies carrying up to five years in prison. Alabama imposes up to 10 years for felony hit and run involving injury or death. Mississippi requires drivers to immediately stop and render aid after any accident; felony charges apply when injuries are involved.

The statute of limitations — your window to file a civil claim — is two years in Alabama and Mississippi, and four years in Florida. Missing this deadline forfeits your right to compensation entirely. If your accident happened in any of these states, contact More 2 You Law immediately to protect your deadline.

Important Alabama note: Alabama follows contributory negligence — one of only a few states that does. Being found even 1% at fault may bar your recovery under certain circumstances. Having an attorney is critical if your accident occurred in Alabama.

Compensation Options for Victims

Being a hit and run victim does not mean you are without financial recourse — even if the driver is never found.

Uninsured Motorist (UM) coverage is your primary safety net when the at-fault driver is unidentified. It covers medical expenses, lost wages, and pain and suffering. Some insurers treat phantom drivers the same as uninsured drivers, enabling a UM claim even without physical contact — though many require witness corroboration.

Other coverage types that may apply include PIP (Personal Injury Protection) for medical costs and lost wages regardless of fault, MedPay for medical and rehabilitation expenses, and collision coverage for vehicle repair or replacement.

Uninsured Motorist

When the driver is found, your options expand significantly. You can file a direct personal injury lawsuit, negotiate with their insurance carrier from a position of established liability, and use their criminal conviction as evidence of negligence in your civil claim.

Full compensable damages in a hit and run case include medical expenses, future medical costs, lost income, reduced earning capacity, vehicle repair or replacement, pain and suffering, emotional distress, and wrongful death damages. If you lost a family member in a hit and run, our wrongful death attorneys can help pursue the full justice your family deserves.

Personal Injury Protection

Get MORE With More 2 You Law

The insurance company on the other side employs adjusters and attorneys whose job is to minimize your payout. You deserve the same professional firepower — and at More 2 You Law, you get it for less than most firms charge.

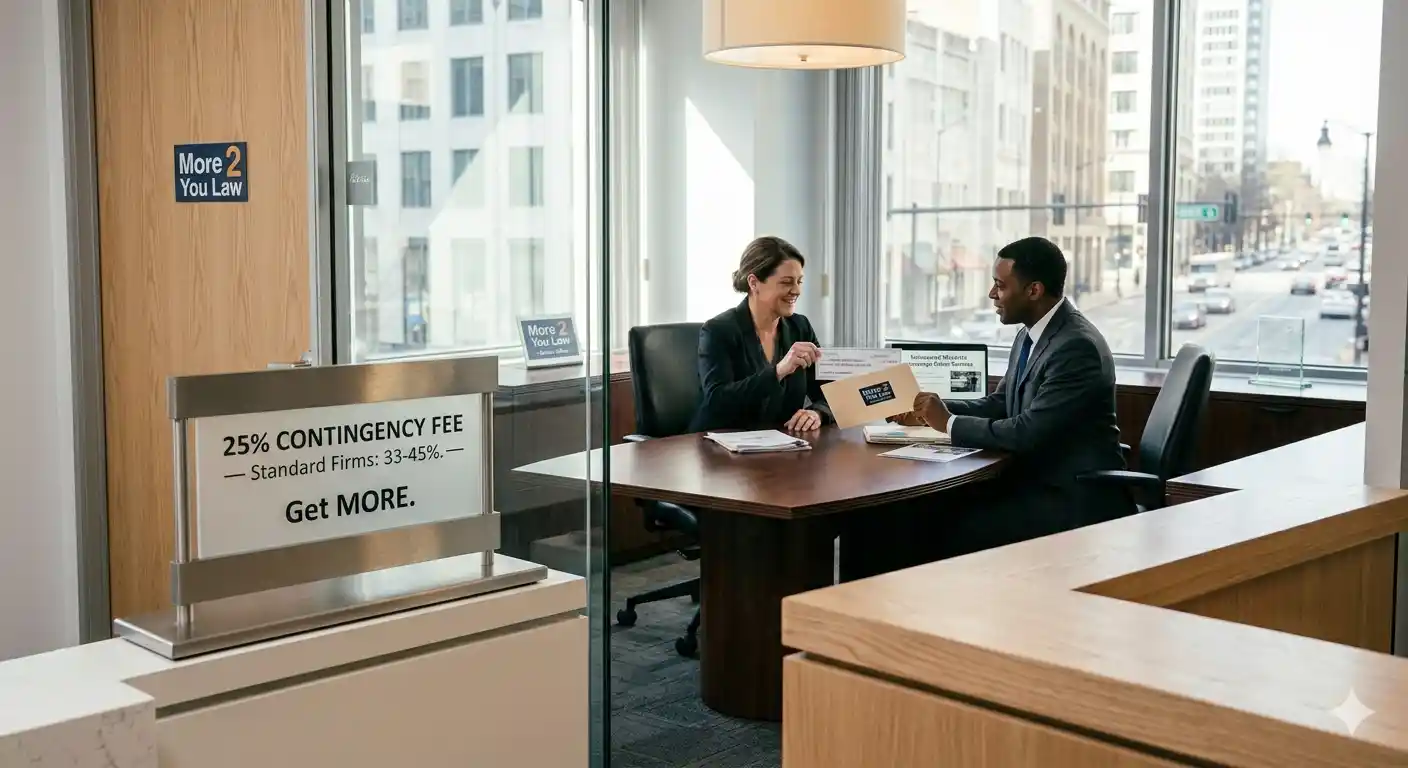
Most personal injury firms take 33–45% of your settlement. More 2 You Law charges just 25%. On a $100,000 settlement, that difference puts an extra $8,000–$20,000 directly back in your pocket.

We handle everything — subpoenaing surveillance footage before retention windows close, negotiating with insurers, tracking your deadlines, and building your full damages picture. You focus on recovering. We focus on getting you MORE.

Start your free consultation now Call toll-free: 888.645.2222 Serving Alabama, Florida, Georgia & Mississippi

A hit and run accident strips you of the one thing every injured person deserves — a driver who stays and answers for what they did. The law exists to compensate you anyway. More 2 You Law exists to make sure you collect every dollar of it — and keep MORE of it when you do.

FAQs

Can I get compensation if the driver is never found?

Yes. Your Uninsured Motorist (UM) coverage is designed exactly for this. File promptly, provide the police report, and let an attorney handle insurer negotiations.

Is a hit and run a felony or misdemeanor? 

It depends on the outcome. Property damage only is typically a misdemeanor. Injury or death escalates the charge to a felony in Alabama, Florida, Georgia, and Mississippi — with sentences reaching up to 15 years.

What if I was partially at fault? 

Florida, Georgia, and Mississippi follow comparative negligence — partial fault reduces your recovery but does not eliminate it. Alabama’s contributory negligence rule is stricter. Call us before assuming you cannot recover.

How long do I have to file a claim? 

Two years in Alabama and Mississippi. Four years in Florida. Georgia allows two years for personal injury claims. Do not wait — evidence and witness memories fade fast.


RECENT POSTS

Contingency Fee Lawyer: How It Works, What You’ll Pay, and What to Ask

Contingency Fee Lawyer: How It Works, What You’ll Pay, and What to Ask

Contingency Fee Lawyer: How It Works, What You’ll Pay, and What to Ask

You’ve been injured. Bills are piling up. You’ve missed work. The last thing you need is to pay an attorney hundreds of dollars per hour before your case even starts. A contingency fee lawyer changes that — you pay nothing upfront, and your attorney only gets paid if they win your case.

Whether it’s gathering evidence, negotiating with insurance companies, or representing clients in court, More 2 You handles every aspect with utmost professionalism and dedication.

What Is a Contingency Fee Lawyer?

A contingency fee lawyer takes your case without charging upfront. Instead of billing by the hour, they collect a percentage of whatever you recover — through a settlement or a court verdict.

If you win, your attorney gets paid from that recovery. If you lose, you owe no attorney fees. That’s what makes legal representation accessible to people who couldn’t otherwise afford it.

If you’ve been hurt because of someone else’s negligence, our personal injury lawyers cover a wide range of cases across Alabama, Florida, Georgia, and Mississippi.

How the Fee Arrangement Works

Before your attorney lifts a finger, both of you sign a written contingency fee agreement. That document states the exact percentage your attorney receives, when it applies, and how case expenses get handled.

The agreement must be in writing — that’s a legal requirement, not a formality. Read every line before you sign.

What Types of Cases Use Contingency Fees

Contingency fees apply most commonly to car and truck accident claims, motorcycle accidents, workers’ compensation cases, slip and fall injuries, medical malpractice, wrongful death actions, and property damage or insurance disputes.

Attorneys don’t use contingency fees in criminal defense or family law. Those cases don’t produce a financial recovery to draw a percentage from, so attorneys bill hourly instead.

settlement check disbursement

How Does a Contingency Fee Lawyer Actually Get Paid?

Most clients know their attorney gets paid from the settlement. What most don’t know is exactly how that money moves. Here’s the full sequence.

The Settlement-to-Payment Process, Step by Step

Step 1 — Your case resolves through a negotiated settlement or a court verdict in your favor.

Step 2 — The settlement check goes to your attorney’s trust account — not directly to you.

Step 3 — Your attorney deducts agreed case expenses — filing fees, deposition costs, expert witness fees.

Step 4 — Your attorney calculates their fee — from the gross amount or post-expense total, per your written agreement.

Step 5 — You receive your share — along with a written disbursement statement showing every deduction.

Always ask for that disbursement statement. If your attorney doesn’t send it automatically, request it immediately.

The Question Most Clients Never Ask

Whether your attorney’s percentage gets calculated before or after expenses are deducted makes a real difference in what you take home. The two methods produce different numbers on the same case.

Ask this question directly before you sign. It belongs in your written agreement — not as a verbal promise.

What Expenses Could You Still Owe If You Lose?

If your case doesn’t succeed, you owe zero attorney fees. That part is straightforward.

But certain out-of-pocket expenses may still apply depending on your agreement — court filing fees, deposition and transcript costs, expert witness fees, and investigation or documentation expenses.

Find the expense clause in your agreement before you sign. Confirm in writing exactly what you owe if the case doesn’t go your way. If a workplace injury is involved, our workers’ compensation page explains how these claims typically unfold and what expenses to watch for.

Contingency Fee vs. Hourly Fee — Which One Fits Your Situation?

The fee structure your attorney uses shapes your financial exposure, their motivation, and how the case gets managed. Here’s what each option actually means for you.

When a Contingency Fee Makes Sense

With a contingency fee, you pay nothing upfront. Your attorney collects only when you win, which means their financial outcome depends directly on yours. If the case is lost, you owe no attorney fees.

This works best when you have no money available to pay an attorney upfront, your case involves a clear injury or documented financial loss, and the expected damages are significant enough to justify a percentage-based fee for both sides.

That covers most auto accident cases, truck accident claims, and slip and fall injuries — the cases More 2 You Law handles every day.

personal injury settlement process

When Hourly Billing Makes Sense

With hourly billing, you pay regardless of outcome, billed in agreed increments from the start. The attorney earns the same whether you win or lose.

Hourly billing fits better when your case doesn’t produce a financial recovery — criminal defense or custody disputes — when you want direct control over how your attorney spends their time, or when the dispute value is low enough that a percentage fee would be disproportionate.

The Hybrid Model

Some attorneys offer a hybrid — a reduced hourly rate paired with a lower-than-standard contingency percentage. The attorney earns partial income regardless of outcome. The client pays less than full hourly billing. Both sides carry some financial risk.

If your case is complex or could run for years, ask whether a hybrid structure is an option. Most clients never think to ask.

personal injury attorney in Alabama

Pros and Cons of Hiring a Contingency Fee Lawyer

This arrangement works well for most clients — but there are real downsides worth knowing before you sign anything.

What Works in Your Favor

No upfront cost. Even if you’re buried in medical debt and can’t work, you can still hire an experienced attorney and pursue the compensation you’re owed.

Aligned incentives. An hourly attorney earns the same amount no matter what happens to your case. A contingency fee attorney only gets paid when you do — so their effort is directly tied to your result.

No attorney fees if you lose. You carry the risk of an unsuccessful case, but not an attorney bill on top of it.

What Works Against You

A percentage of your recovery goes to your attorney. It’s the cost of access to representation. For most clients it’s worth it — particularly when the other option is negotiating alone against an insurance company.

Attorneys can and do turn cases down. If liability is unclear or damages are low, a firm may decline. They assess financial risk before committing time and money without guaranteed payment.

Fast settlements still carry the full fee. If your case wraps up in two weeks, your attorney collects the same agreed percentage as if they’d worked it for two years. Be sure you’re comfortable with that number before signing.

How Attorneys Decide Whether to Take Your Case

Before agreeing to represent you, most attorneys look at the strength and clarity of the evidence, total damages at stake, hours and upfront money the case will require, estimated duration, and how the case compares to others they could be handling instead.

A rejection doesn’t always mean your claim is weak. Sometimes the economics don’t work for that firm. If you’ve suffered a serious injury and aren’t sure whether you have a viable case, our catastrophic brain injury and wrongful death pages explain what typically qualifies for representation.

How to Read and Negotiate a Contingency Fee Agreement

5 Clauses to Read Before You Sign

  1. The exact percentage — and whether it goes up if the case proceeds to trial rather than settling.
  2. Fee calculation method — does the percentage apply before or after expenses are deducted? This one clause determines how much you actually take home.
  3. Expense responsibility if you lose — which costs stay your obligation regardless of outcome.
  4. Expert witness and deposition costs — when they get billed and whether they come out of the recovery or get charged separately.

5. Termination clause — what you owe financially if you fire your attorney or switch firms mid-case.

Contingency Fee Agreement

Can You Negotiate the Percentage?

Yes — and most clients don’t realize it. The number your attorney quotes first is not final.

Your position is strongest when your case involves significant damages and clear liability, the evidence is solid and a long legal battle is unlikely, and you’ve spoken with more than one attorney.

Ask for a sliding scale — a lower percentage if the case settles before trial, a higher one if it goes to a verdict. Whatever you agree on must appear in the written agreement before work begins. If you’re dealing with a motorcycle accident or a medical malpractice claim — both complex, high-value case types — this conversation is worth having at the very first meeting.

Red Flags in a Fee Agreement

Walk away or ask hard questions if you see vague language around who pays expenses if you lose, no written explanation of how the percentage gets calculated, pressure to sign before reading the full document, no termination or withdrawal policy, or verbal promises that don’t appear anywhere in writing.

A good attorney expects you to push back. If yours doesn’t, pay attention to that.

contingency fee

What to Look for When Hiring a Contingency Fee Lawyer

The right attorney matters more than the lowest percentage. One who fights for your full case value puts more in your pocket than one who settles quickly for less than you deserve.

Questions to Ask Before You Hire Anyone

  • Does your percentage increase if we go to trial?
  • Do you calculate your fee before or after expenses are deducted?
  • What costs am I responsible for if the case doesn’t succeed?
  • What’s your honest read on my case — strength, value, timeline?
  • Who handles my case day to day, and how often will I hear from you?

What a Trustworthy Attorney Actually Does

A good contingency fee attorney explains the fee agreement without being asked, puts every cost in writing before you sign, gives you an honest case assessment instead of a guarantee, has real experience with your type of case, and returns your calls.

You’ve already dealt with the injury, the insurance company, and the financial pressure that followed. The attorney you hire should make the next step easier — not add to the confusion. At More 2 You Law, we answer every question upfront, put everything in writing, and fight to get you the most possible.

We serve clients across Alabama, Florida, Georgia, and Mississippi. Whether you’re dealing with an auto accident, or you’re still asking who pays your medical bills while your case is pending — call us at 888-645-2222 or start your free case evaluation here.

FAQs

Do I pay a contingency fee lawyer if I lose?

No — you owe zero attorney fees if your case is unsuccessful. Out-of-pocket expenses such as filing fees, deposition costs, or expert witness fees may still apply depending on your written agreement. Check the expense clause before signing.

What types of cases use contingency fee lawyers?

Contingency fees are standard in personal injury, car accidents, truck accidents, workers’ compensation, slip and fall, medical malpractice, wrongful death, and property damage cases. They’re generally not available for criminal defense or family law, since those cases don’t produce a financial recovery.

Can I negotiate the contingency fee percentage?

Yes. The first number your attorney gives you is negotiable, particularly on strong cases with clear liability and significant damages. Any change must be confirmed in your written agreement before work starts.

How does the attorney get paid after a settlement?

The settlement check goes to your attorney’s trust account. They deduct agreed case expenses, apply their fee percentage, then send you your share along with a written disbursement statement showing every deduction.

Does a contingency fee agreement have to be in writing?

Yes, always. A verbal arrangement isn’t enforceable in most jurisdictions. The written agreement must state the percentage, how it’s calculated, and what expenses you remain responsible for regardless of outcome.

What is a hybrid contingency fee?

A hybrid combines a reduced hourly rate with a lower contingency percentage. The attorney earns partial income even if the case is lost. The client pays less than full hourly billing. Both sides share the financial risk.

How is a contingency fee different from a retainer?

A retainer is money you pay upfront to secure your attorney’s time, billed against at an hourly rate. A contingency fee requires nothing upfront — your attorney collects only if the case resolves in your favor.

What happens to expenses if I switch attorneys mid-case?

It depends on your termination clause. Some agreements let you leave without owing anything until the case resolves. Others require you to cover expenses already incurred. Read this clause carefully. If you’re in a dispute with your current firm, our breach of contract page explains your rights.


RECENT POSTS

Translate »